The letter arrived on a Tuesday. It did not look like an eviction notice. It looked like an invoice for a minor municipal nuisance, a slip of pale paper folded into a windowed envelope that fluttered down among the junk mail and grocery circulars like an autumn leaf.
The amount was five hundred eighty-eight dollars and twenty-one cents.
To a household juggling grocery prices, car insurance, and the quiet, creeping anxiety of modern inflation, five hundred dollars is a gut punch. It requires shuffling money from savings or delaying a dentist appointment. But it is not catastrophic. It is something you figure out. Except, in this particular case, the arithmetic of local governance does not wait for you to figure it out. It operates on a cold, relentless clockwork of its own.
Consider what happens when a minor debt slips through the cracks of a busy life. Maybe the notice went to an old address. Maybe an email confirmation failed to register. Maybe illness struck, or a parent died, or the sheer weight of daily survival crowded out a single line item on a spreadsheet. Life is messy. Municipal bureaucracy is not.
By the time the system finished compounding interest, administrative fees, legal notices, and statutory penalties, that initial slip of five hundred dollars had mutated. It ballooned to five thousand two hundred sixty-eight dollars.
Still, a manageable sum, one might think. A steep penalty, yes, but hardly a fatal blow.
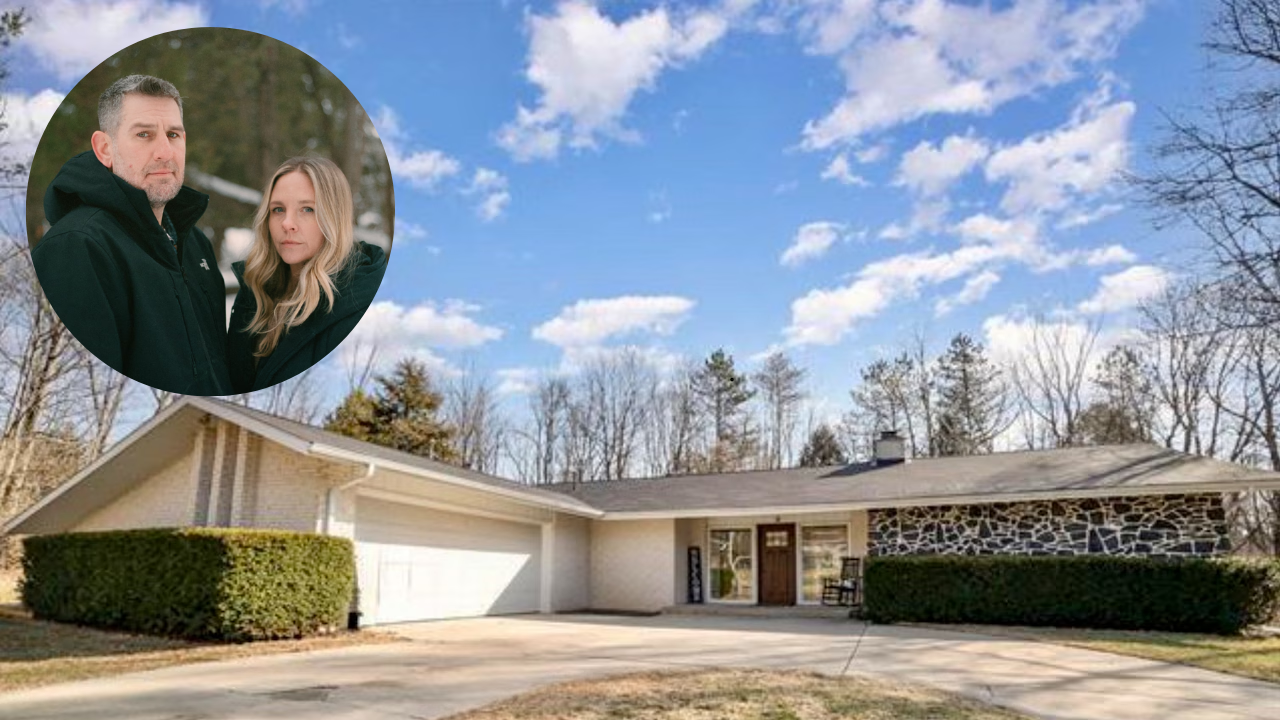
Then comes the final, incomprehensible pivot of the machine. The property attached to this debt—a modest, completely mortgage-free home valued at fifty-nine thousand seven hundred fifty-nine dollars—was seized. Not borrowed against. Not placed in escrow. Seized outright, liquidated, and sold. The owners lost a lifetime of accumulated shelter, equity, and peace of mind over a discrepancy that amounted to less than one percent of the home's value.
How does a society that prides itself on property rights, due process, and the sanctity of the home allow a system of legal plunder to operate in broad daylight?
To understand the mechanics of this quiet tragedy, we have to look past the cold statutes and examine the human architecture of tax foreclosures. (Note: While the exact details mirror documented cases of municipal home equity theft in states like Michigan and Nebraska before landmark supreme court rulings, the scenario serves to illustrate a systemic vulnerability that still threatens homeowners nationwide.)
The Anatomy of a Snowball
We are taught to believe that our homes are our castles. We spend thirty years trading our youth and labor for the deed, enduring interest rates, property taxes, and home repairs, all under the comforting illusion that once the mortgage is burned, the roof over our heads is permanently ours.
The state, however, views things differently.
Property taxes are the primordial lien. They sit above the bank, above personal loans, above everything. If you owe income tax, the government might garnish your wages. If you default on a credit card, collectors will hound your phone. But fail to pay the municipality its due—even by a margin smaller than a monthly grocery bill—and the government holds a blunt instrument: the tax lien sale.
In many jurisdictions, local governments do not collect these debts themselves. They package them up and sell them to private tax lien investors. These investors are not romantic benefactors; they are financial entities seeking a return on investment. And boy, do they get it.
When an investor purchases a tax lien, they acquire the right to collect the back taxes plus statutory interest rates that can range anywhere from twelve to thirty-six percent annually, depending on state law. Suddenly, a minor municipal oversight becomes a high-yield asset.
Every fee, every certified letter sent, every legal filing executed by the investor’s attorneys gets tacked onto the homeowner’s balance. The meter runs constantly. A late fee triggers a processing fee. A processing fee triggers a legal notice fee. The debt feeds on itself, swelling in the dark while the homeowner remains blissfully, fatally unaware that the math has turned predatory.
The Invisible Trap
Imagine living for decades in a small town. You raised your children in the hallway where pencil marks on the door frame measure their growth in inches. You painted the kitchen yellow yourself. The mortgage was paid off years ago—a milestone celebrated with a quiet dinner and a sigh of profound relief.
You think you are safe.
Then comes the legal threshold where the accumulated debt, bloated by administrative alchemy, permits the county or the private lien holder to foreclose. In the worst-performing states, this process historically allowed governments to practice what can only be described as state-sanctioned equity theft.
Under these archaic rules, if a home was worth sixty thousand dollars and the total tax debt—with all penalties and fees attached—was five thousand dollars, the county could foreclose on the property, sell it at auction to satisfy the five thousand dollar debt, and pocket the remaining fifty-five thousand dollars.
Let that sink in.
The government kept the change. Not just a reasonable penalty for late payment, but the entire accumulated equity of a family's life savings. If a bank forecloses on a mortgage, the surplus funds after the debt is paid must legally be returned to the homeowner. But under legacy tax foreclosure laws in several states, municipalities treated the surplus like a windfall bonus.
It is the financial equivalent of executing someone for a minor traffic violation and keeping their car, their wallet, and the cash in their pockets because they failed to pay a parking ticket.
The Turning Tide of Justice
Fortunately, the law is slowly catching up to the cruelty of this mechanism.
In recent years, landmark legal battles have begun to dismantle these predatory practices. The United States Supreme Court delivered a monumental unanimous ruling in Tyler v. Hennepin County, establishing a bedrock constitutional principle: when a government takes a property for unpaid taxes, it cannot keep the surplus equity beyond what is owed. Doing so violates the Takings Clause of the Fifth Amendment.
It was a rare, unambiguous victory for common sense and human dignity. An acknowledgement that the state's interest is in collecting the tax revenue it is owed, not in seizing windfalls by stripping citizens of their generational wealth.
Yet, rulings in high courts do not automatically rewrite the administrative habits of thousands of local municipalities overnight. The machinery is heavy, bureaucratic, and resistant to change. Thousands of counties still operate in gray areas, navigating legacy rules while homeowners continue to slip through the cracks of communication and digital bureaucracy.
What We Must Protect
The real danger of a system like this is not just the loss of money; it is the erosion of trust between the citizen and the state.
A tax system must be firm, fair, and transparent. It must ensure that communities have the funding they need for schools, roads, and emergency services. No one argues that taxes shouldn't be paid. But the enforcement mechanism must scale proportionally to the offense.
When a five-hundred-dollar oversight can trigger the total vaporization of a mortgage-free home, the system has ceased to be a tool of civic maintenance and has become something else entirely: a trap for the vulnerable, the elderly, the overwhelmed, and the unrepresented.
Check your mail. Verify your escrow accounts. Ensure that your local tax assessor has your current phone number and physical address. In a digital world where our lives are mediated by automated notifications and spam filters, it is terrifyingly easy for a small error to be amplified by predatory math into a life-altering catastrophe.
The home you own is more than an asset on a balance sheet. It is the physical anchor of your existence, the place where you sleep safely at night, shielded from the chaos of the outside world.
Do not let a clerical error, amplified by predatory arithmetic, turn that sanctuary into ash.