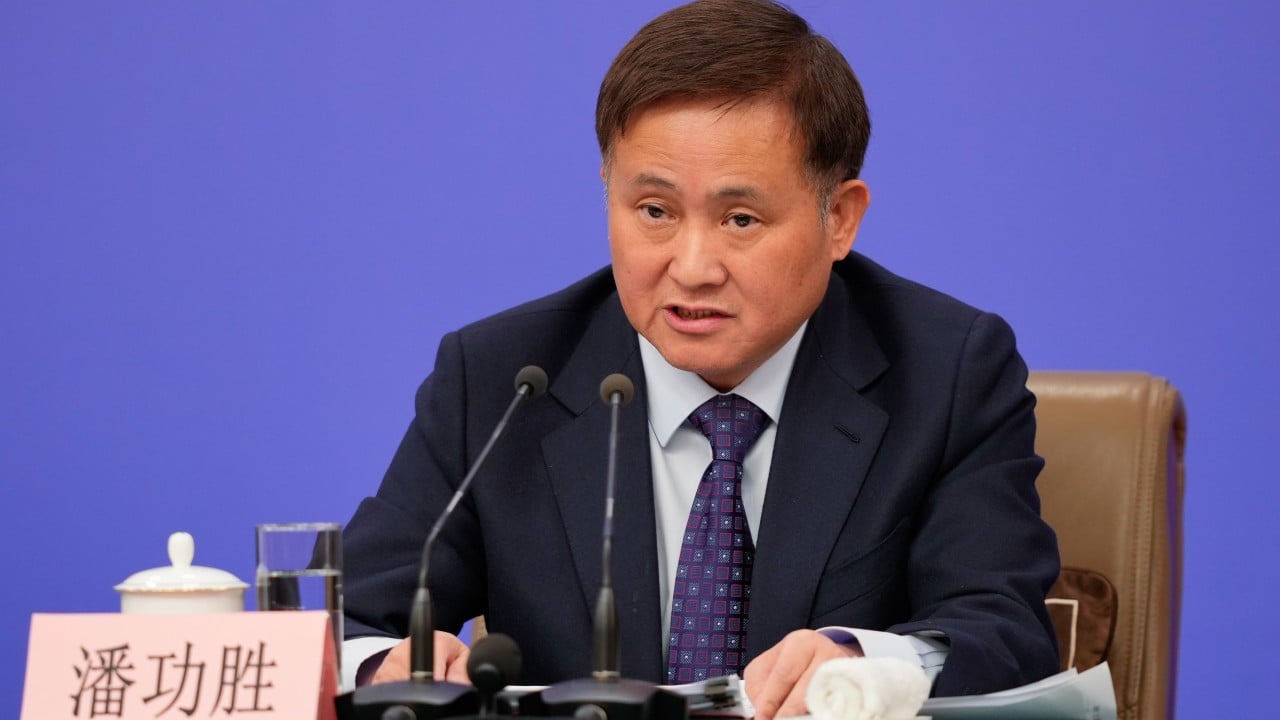
Blaming exchange rates for global trade imbalances is a tempting shortcut. It feels clean, technical, and easy to point at on a chart. Yet People's Bank of China Governor Pan Gongsheng argued in October 2026 that currency shifts alone cannot resolve global imbalances, calling instead for joint policy action across both surplus and deficit economies.
I find that argument hard to dismiss if you look at what actually drives trade gaps today. You can move a currency up or down, sure, but currency math doesn't magically fix weak household demand in one country or oversized fiscal deficits in another.
Let's be honest. Political debates love a single villain and a single lever. When China's merchandise trade surplus widened to $1.2 trillion in 2025, plenty of commentators reached straight for the renminbi and treated currency appreciation like a magic dial. Turn it up, shrink the surplus, save domestic factories elsewhere. Simple, right?
Not quite. That pitch skips over why goods are flowing outward at that scale in the first place.
Why global imbalances keep widening past exchange rates
Trade surpluses and deficits are accounting identities before they are currency stories. At the macro level, a country's current account balance reflects the gap between national saving and domestic investment. If domestic demand cools off—especially big-ticket investment—while saving stays elevated or falls more slowly, excess production has to go somewhere, and net exports expand to absorb it.
China's property slump is a prime example of how domestic mechanics reshape external trade. Real estate used to anchor Chinese credit creation, local government finances, household wealth perceptions, and construction-linked investment. When housing struggles, domestic demand takes a hit, particularly investment demand. Research from the CF40 Institute notes a broader historical pattern: housing busts have repeatedly coincided with stronger external balances, including in past episodes involving the United States and Japan.
Even when nominal exchange rates look relatively steady against the dollar or a currency basket, real exchange rates can shift quietly. Soft domestic demand and subdued inflation at home alongside higher inflation abroad can leave a currency looking cheaper in real terms without a dramatic headline move on a screen. Treating that gap as a pure currency-manipulation story misses the domestic slowdown sitting underneath it.
The real limits of currency appreciation as a quick fix
Here's where policy wishful thinking runs into friction. If an exchange rate is held down purely by heavy, artificial intervention to subsidize exports, a move toward market pricing or appreciation can help clear that distortion. When weak domestic demand is doing the heavy lifting, though, forcing a sharp appreciation first can backfire.
Think about what happens if the renminbi jumps abruptly while domestic demand is still finding its footing. Export-oriented manufacturers get squeezed by higher prices abroad, which can ripple back into employment, capital spending, and local confidence at home. A sudden currency jump doesn't automatically cure a sluggish property sector or convince cautious households to spend more.
There's also a global price twist that critics of the currency-only fix tend to gloss over. China has become a major price anchor across large swaths of global manufacturing, meaning its producer prices affect goods prices worldwide even when products aren't shipped directly across the border. Cheaper Chinese goods have helped keep a lid on manufactured goods inflation in advanced economies. Force a sharp appreciation, and you risk exporting cost-push price pressure right back to central banks already wrestling with sticky inflation or shifting supply chains.
Nor does currency appreciation guarantee that factories suddenly open in Europe or productivity surges in the United States. Industrial competitiveness rests on supply chains, energy and input costs, automation, scale, and R&D—not just exchange rates.
What joint action actually looks like for surplus and deficit economies
Pan's push for shared responsibility gets at an uncomfortable truth: one country can't rebalance the world economy by itself. In his remarks around international policy meetings in October 2026, he pointed to responsibilities on both sides—urging deficit economies to curb fiscal deficits and lift domestic savings, while calling on surplus economies to support domestic consumption and investment and follow through on medium- and long-term plans.
That division of labor makes sense on paper, though it's politically brutal in practice. Let's break down what each side actually has to confront:
- Deficit economies face fiscal trade-offs: Running large fiscal deficits sustains domestic demand and imports, but keeping deficits wide indefinitely makes external rebalancing uphill work. Cutting deficits or raising national savings isn't painless, because voters usually dislike spending cuts or tax hikes more than they dislike trade deficits.
- Surplus economies face demand and structural shifts: Boosting domestic consumption and productive investment sounds straightforward, yet household caution, balance-sheet repair, and structural incentives don't flip overnight. On the policy side, the People's Bank of China has emphasized letting market forces play a decisive role in the exchange rate, maintaining a moderately loose monetary stance to support stability, reshaping its growth model, and starting to report foreign exchange operation data to the IMF from 2027.
- Credibility requires follow-through: Big summits produce plenty of communiqués, and very few of them bind domestic politicians six months later. Follow-through on medium- and long-term commitments—plus transparency—matters way more than tough talk.
I'm skeptical that any single policy package will solve global imbalances cleanly anytime soon. Geopolitical tensions, industrial subsidies, trade frictions, and uneven growth cycles pull governments in opposite directions. Still, arguing that joint action beats a currency-only fix isn't a cop-out—it's a recognition that trade gaps are symptoms of deeper domestic choices.
Practical next steps for tracking the rebalancing debate
If you follow global macro, trade, or cross-border business strategy, don't stop at daily exchange-rate headlines. Watch the underlying signals that actually move trade balances over time.
- Track domestic demand indicators ahead of FX moves: Watch housing stabilization, retail sales, and capital expenditure alongside currency quotes to see whether external surpluses are shrinking because domestic demand is recovering or simply because trade flows are shifting.
- Watch fiscal projections in major deficit economies: Keep an eye on budget deficits and savings rates in large importing economies, since persistent fiscal gaps keep import demand elevated regardless of currency swings.
- Read primary central bank and IMF disclosures: Follow official central bank statements, IMF consultations, and upcoming foreign exchange reporting disclosures rather than relying on second-hand soundbites.
- Stress-test supply chains for policy shocks: If you run or advise a business exposed to cross-border trade, model scenarios for tariffs, shifting input costs, and currency volatility rather than betting on a quick macro fix.