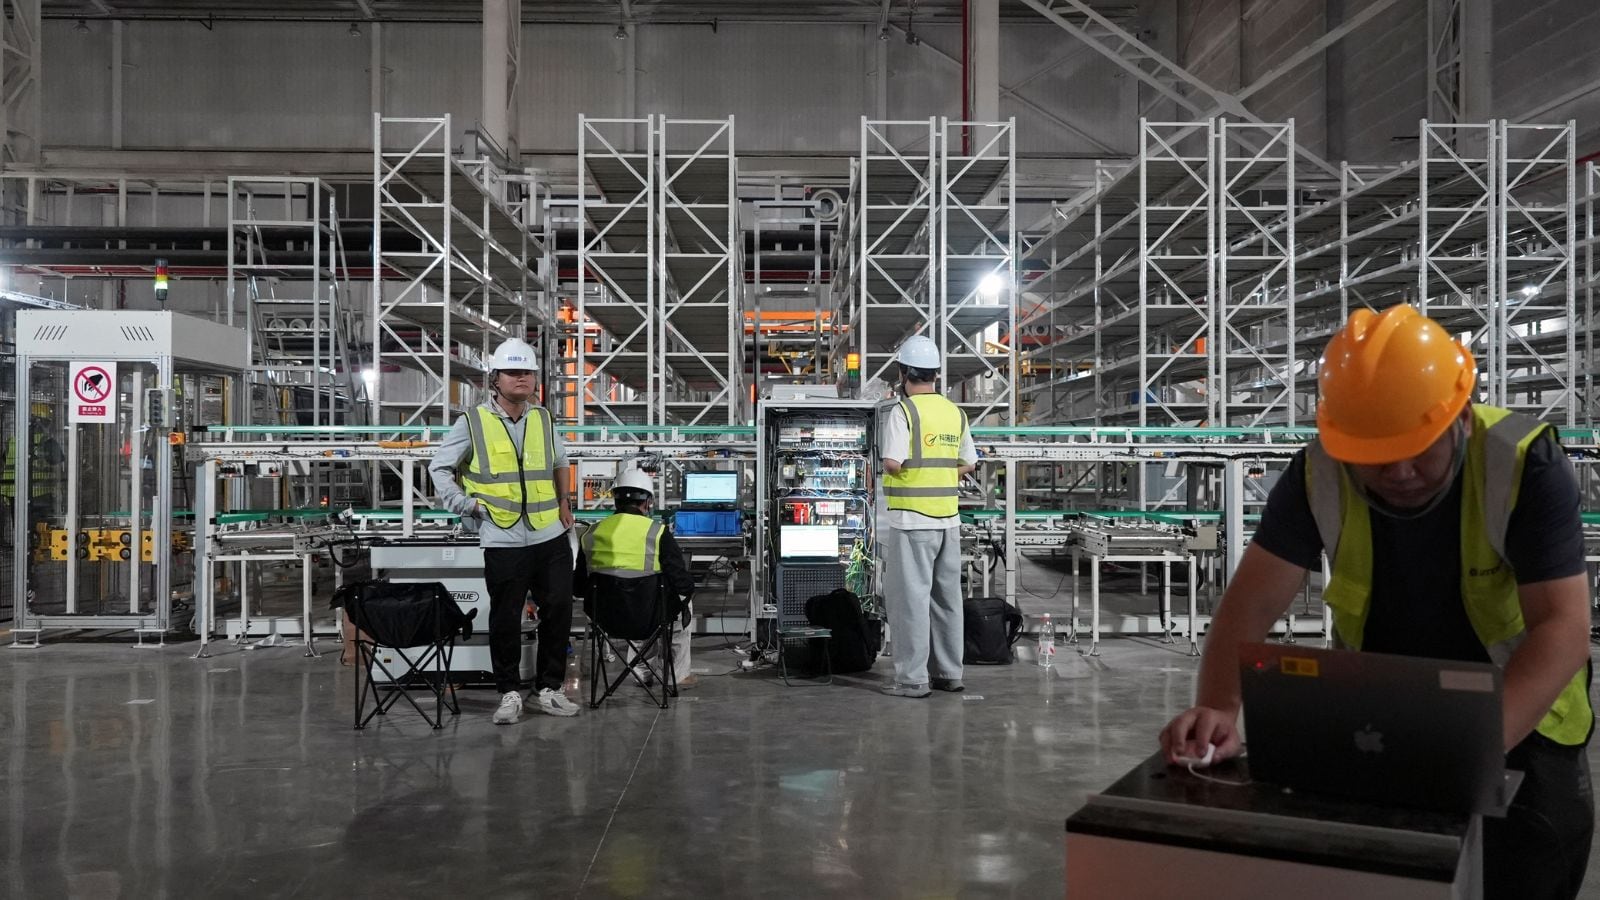
John Healey stands at a podium and offers a familiar script. Westminster wants an industrial revolution. Ministers speak of renewed ambition, strategic manufacturing sovereignty, and a break from
Labour Promises a British Industrial Renaissance But Treasury Reality Bites Hard
business
news For a different perspective, check out: this related article.
John Healey stepped up to the conference podium with a mandate that sounded remarkably familiar to anyone who spent the 1990s and 2000s watching successive Westminster administrations try to resurrect Britain's rusting manufacturing backbone. The pitch was direct. A new age of industrialisation for the United Kingdom. Factories humming again, green energy transition fueling regional wealth, and state-backed capital turning economic stagnation into a productivity boom.
It is a seductive narrative. Whitehall loves a grand industrial strategy because it projects purpose, control, and long-term vision. But political rhetoric rarely survives first contact with the Treasury. Behind the optimistic speeches about modern supply chains and strategic manufacturing lie deep structural deficits, a chronic lack of private capital depth, and a tax regime that punishes heavy capital expenditure. Further coverage on this trend has been published by Forbes.
To understand why this latest vision faces an uphill battle, we have to look past the party conference applause and examine the mechanical machinery of the British state.
The Structural Trap of British Manufacturing
Britain stopped making things on a mass scale not because politicians lacked ambition, but because the nation's financial architecture fundamentally shifted away from physical assets. For four decades, the British economy prioritized financial services, real estate transactions, and consumption-driven growth.
When a government tries to reverse that trajectory with a speech, it collides with a severe shortage of institutional engineering. You cannot decree an industrial renaissance into existence simply by setting up another advisory council or rebranding regional development funds.
The core problems remain stubbornly intact:
- Grid Capacity: Modern automated factories, green steel production, and gigafactories require immense, reliable power inputs. The current National Grid transmission infrastructure is decades behind where it needs to be to support a rapid industrial expansion.
- Skills Deficit: Decades of underinvestment in vocational training and technical colleges have left a generational gap in advanced engineering capabilities.
- The Scale-Up Valley of Death: British startups invent world-class technology in university labs, but they routinely get bought out by foreign competitors or move abroad because domestic venture capital is risk-averse compared to Silicon Valley or Shenzhen.
Healey’s blueprint acknowledges these friction points in broad strokes. Yet, acknowledging a bottleneck is not the same as dismantling it.
Where the Money Actually Goes
Governments love state aid announcements because the headline numbers sound staggering. Billions pledged for green transitions, millions earmarked for regional aerospace hubs.
In practice, public money in the British system rarely acts as the primary engine. Instead, it serves as a risk-mitigation cushion for private multinational corporations that demand tax breaks and subsidies before they commit a single brick to a foundation. If the incentives dip or regulatory certainty wavers, these corporations pivot elsewhere with zero corporate loyalty to British regional regeneration.
Consider the recent history of automotive and battery manufacturing investments. Every major facility announcement is greeted as proof that the industrial strategy is working. Yet, a closer examination of the balance sheets reveals a heavy reliance on taxpayer-funded sweeteners just to make the project economically viable against European and American alternatives.
When the state acts as the primary financial backstop for private risk, the taxpayer absorbs the downside while private shareholders capture the upside. That is not industrial policy; that is corporate welfare wrapped in patriotic branding.
The Regional Disconnect
The promise of industrialisation always targets the regions left behind by the deindustrialisation waves of the 1980s. Former mining towns, ship-building ports, and textile hubs are told that their time has come round again.
Yet, local municipal authorities lack the fiscal autonomy required to execute complex long-term economic transformations. Westminster retains tight control over taxation powers and major spending allocations. A town council in South Yorkshire might have a brilliant vision for a clean-tech manufacturing cluster, but they have to beg central departments for piecemeal grants that take years to approve and disburse.
Until genuine devolution of fiscal power accompanies industrial grand strategy, local economies will remain at the mercy of shifting departmental priorities in Whitehall. Every time a new cabinet minister takes over, the strategic playbook changes, leaving regional development projects stranded in administrative limbo.
The Global Reality Check
Britain is attempting this industrial pivot at a time when global trade dynamics are shifting toward aggressive protectionism. The United States deployed the Inflation Reduction Act with hundreds of billions in direct subsidies designed to suck green manufacturing away from Europe and the UK. The European Union responded with its own loosened state aid rules and industrial masterplans.
In this high-stakes global auction, Britain’s fiscal headroom is severely constrained. The national debt sits at historic highs, debt interest payments consume a massive slice of annual tax revenues, and public services are already buckling under chronic underfunding.
Promising an industrial revolution without the chest of gold to sustain a multi-decade subsidy war is an exercise in political optimism. Without deep structural reform to taxation, energy pricing, and technical education, the new age of industrialisation risks becoming another footnote in a long line of well-intentioned political speeches that collided with economic reality.